Maximizing 2026 401(k) Contributions: Strategies for the $23,000 Limit
Anúncios
Maximizing your 2026 401(k) contributions is essential for long-term financial health, involving a clear understanding of contribution limits and proactive saving strategies.
Understanding how to maximize your 2026 401(k) contributions: strategies for a $23,000 limit is more important than ever for securing your financial future. As retirement planning evolves, staying informed about the latest contribution limits and leveraging effective strategies can significantly impact your long-term wealth accumulation.
Understanding the 2026 401(k) Contribution Limit
The 2026 401(k) contribution limit is a critical figure for anyone serious about retirement savings. This limit, set by the IRS, dictates the maximum amount an individual can contribute to their 401(k) plan in a given year, excluding employer contributions. For 2026, this limit is projected to be $23,000, representing a significant opportunity for many to bolster their retirement nest egg.
Anúncios
It’s vital to recognize that this limit applies specifically to employee deferrals. Any contributions made by your employer, such as matching contributions or profit-sharing, are separate and do not count towards your personal $23,000 ceiling. This distinction is crucial for strategic planning, as it means the total amount flowing into your 401(k) could be substantially higher.
How Contribution Limits are Determined
The IRS regularly adjusts 401(k) contribution limits to account for inflation and economic changes. These adjustments are typically announced in the fall of the preceding year, providing individuals and employers time to plan. Understanding the methodology behind these adjustments helps in anticipating future changes and adapting saving strategies accordingly.
Anúncios
- Inflation Adjustment: Limits are primarily indexed to inflation, ensuring the real value of contributions remains consistent over time.
- Economic Factors: Broader economic trends and legislative changes can also influence these limits, though less frequently.
- IRS Announcements: Official announcements from the IRS are the definitive source for confirmed limits each year.
Staying informed about these limits is the first step toward maximizing your retirement savings. Failing to meet the limit means leaving potential tax advantages and compound growth on the table, which can have a considerable impact over several decades of saving.
Leveraging Catch-Up Contributions for Older Savers
For individuals aged 50 and over, the opportunity to accelerate retirement savings is enhanced through catch-up contributions. These provisions allow older workers to contribute an additional amount beyond the standard limit, recognizing that they have fewer years until retirement to save.
In 2026, the catch-up contribution limit for 401(k) plans is expected to be an additional $7,500, bringing the total potential contribution for those eligible to $30,500. This extra saving capacity can be a game-changer, especially for those who started saving later in their careers or experienced periods of lower contributions.
Eligibility and Benefits of Catch-Up Contributions
Eligibility for catch-up contributions is straightforward: you must be age 50 or older by the end of the calendar year for which the contributions are made. There are no income restrictions or other complex criteria. This makes it an accessible and powerful tool for a significant portion of the workforce.
- Accelerated Growth: An extra $7,500 annually, coupled with compound interest, can significantly boost your retirement fund.
- Tax Advantages: Like regular 401(k) contributions, catch-up contributions are typically made on a pre-tax basis, reducing your current taxable income.
- Closing Gaps: It provides an excellent opportunity to catch up if your retirement savings are not where you’d like them to be.
Incorporating catch-up contributions into your financial plan should be a priority if you qualify. It’s a direct path to supercharging your retirement savings and making up for lost time, ensuring a more comfortable and secure future.
Strategies for Reaching the $23,000 Limit
Hitting the $23,000 401(k) contribution limit in 2026 requires more than just good intentions; it demands a deliberate strategy. Many people aim to contribute the maximum but fall short due to various financial pressures or a lack of systematic planning. Implementing a consistent approach is key.
One of the most effective strategies is to automate your contributions. Setting up automatic deductions from each paycheck ensures that you are consistently saving without having to make a conscious decision every pay period. This ‘set it and forget it’ method helps maintain discipline and keeps you on track towards your goal.
Payroll Deduction Optimization
To reach $23,000, you need to divide this amount by the number of pay periods in a year. For example, if you are paid bi-weekly (26 pay periods), you would need to contribute approximately $884.62 per paycheck. Adjusting your payroll deductions to meet this target from the beginning of the year prevents a last-minute scramble.
Consider increasing your contribution percentage each year, even by a small amount like 1% or 2%. This gradual increase, often timed with salary raises, makes it easier to absorb the higher contribution without feeling a significant impact on your take-home pay. This incremental approach is often referred to as ‘saving more tomorrow’ and can be highly effective over time.
Another powerful strategy is to direct any windfalls, such as bonuses, tax refunds, or unexpected inheritances, directly into your 401(k) if your plan allows for one-time contributions. These lump sums can help you reach the limit faster or make up for any shortfalls earlier in the year.
Maximizing Employer Matching Contributions
Employer matching contributions are essentially free money for your retirement. Failing to contribute enough to receive the full employer match is one of the most common and costly mistakes employees make. This is a crucial component of maximizing your 2026 401(k) contributions.
Most employers offer a match up to a certain percentage of your salary, provided you contribute at least that much. For instance, an employer might match 100% of your contributions up to 3% of your salary, and then 50% on the next 2%. Understanding your specific employer’s matching formula is paramount to ensure you’re not leaving any money on the table.
Understanding Your Company’s Match Program
It is highly recommended to contribute at least enough to get the full employer match, even if you cannot reach the $23,000 personal contribution limit. This should be your absolute minimum contribution target.
- Review Plan Documents: Carefully read your 401(k) plan documents or speak with your HR department to understand the exact matching terms.
- Calculate Your Minimum: Determine the precise percentage of your salary you need to contribute to unlock the maximum employer match.
- Prioritize the Match: Make receiving the full match a non-negotiable part of your financial plan, as it offers an immediate, guaranteed return on your investment.
Beyond the match, if your financial situation allows, continue contributing beyond that threshold up to the $23,000 personal limit (or $30,500 with catch-up contributions). The combination of your contributions, employer match, and tax-deferred growth can lead to substantial retirement savings.
Considering a Roth 401(k) Option
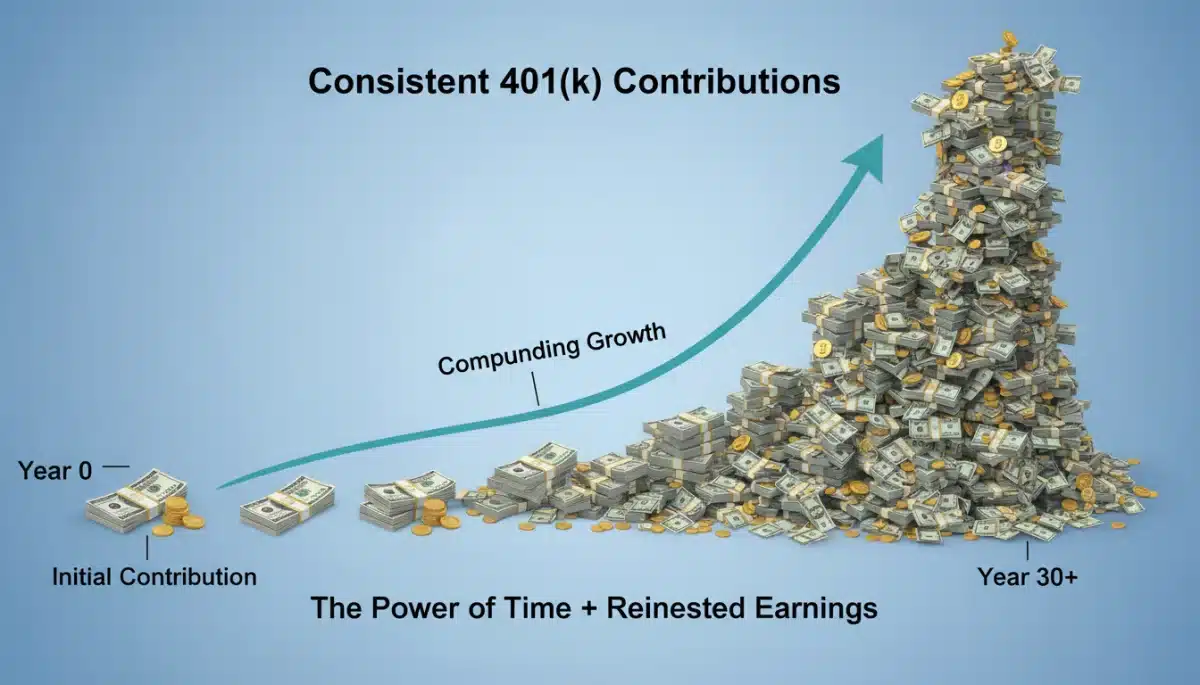
While traditional 401(k)s offer pre-tax contributions and tax-deferred growth, the Roth 401(k) provides a different, yet equally powerful, tax advantage: tax-free withdrawals in retirement. This option is becoming increasingly popular, especially for those who anticipate being in a higher tax bracket during retirement than they are today.
A Roth 401(k) means your contributions are made with after-tax dollars. While you don’t get an immediate tax deduction, all qualified withdrawals in retirement—including all earnings—are completely tax-free. This can be incredibly valuable, particularly as tax rates are unpredictable in the distant future.
Deciding Between Traditional and Roth
The decision between a traditional and Roth 401(k) often comes down to your current income and your projected income in retirement. If you are currently in a high tax bracket, the immediate tax deduction of a traditional 401(k) might be more appealing. If you expect your income (and thus your tax bracket) to be higher in retirement, a Roth 401(k) could be the better choice.
- Current Tax Bracket: Evaluate if you benefit more from a tax deduction now or tax-free income later.
- Future Tax Rates: Consider the likelihood of higher or lower tax rates in retirement.
- Diversification: Some individuals choose to contribute to both a traditional 401(k) and a Roth IRA, or split contributions within their 401(k) if both options are available, to diversify their tax strategy.
Many plans now offer both traditional and Roth 401(k) options, giving you flexibility. It’s a choice that warrants careful consideration, potentially with the help of a financial advisor, to align with your personal financial outlook and retirement goals.
Advanced 401(k) Strategies and Considerations
Beyond simply hitting the contribution limit, there are several advanced strategies and considerations that can further optimize your 401(k) for long-term growth and tax efficiency. These approaches can be particularly beneficial for high-income earners or those with complex financial situations.
One such strategy is the ‘mega back-door Roth,’ which involves contributing after-tax dollars to your 401(k) plan (if permitted), and then converting those funds to a Roth IRA. This allows individuals to bypass income limitations typically associated with Roth IRA contributions, significantly increasing their tax-free retirement savings.
Understanding Your Plan’s Investment Options
The investment choices within your 401(k) plan are just as important as the contribution amounts. A well-diversified portfolio aligned with your risk tolerance and time horizon can significantly impact your returns. Don’t simply set up contributions and forget about the underlying investments.
- Asset Allocation: Ensure your investments are appropriately allocated across different asset classes (stocks, bonds, real estate, etc.) based on your age and risk profile.
- Fund Selection: Choose low-cost, diversified index funds or ETFs over actively managed funds with higher fees, which can erode long-term returns.
- Regular Rebalancing: Periodically review and rebalance your portfolio to maintain your desired asset allocation and risk level.
Another consideration is understanding your plan’s vesting schedule for employer contributions. While your own contributions are always 100% yours, employer contributions may take several years to fully vest. Be aware of this if you anticipate changing employers in the near future, as it could impact the amount of employer match you ultimately receive.
The Importance of Regular Review and Adjustment
Financial planning is not a one-time event; it’s an ongoing process. To truly maximize your 401(k) contributions and ensure your retirement goals remain on track, regular review and adjustment of your strategy are essential. Life circumstances, market conditions, and tax laws can all change, necessitating tweaks to your approach.
At least once a year, preferably at the beginning of the year, take the time to review your 401(k) contributions. Verify that you are on pace to hit the $23,000 limit (or $30,500 if eligible for catch-up). If your income has increased, consider raising your contribution percentage to align with your enhanced earning power.
Key Areas for Annual Review
Beyond contribution amounts, several other aspects of your 401(k) and overall financial plan warrant annual attention:
- Investment Performance: Assess how your chosen funds are performing relative to their benchmarks and your expectations.
- Risk Tolerance: Re-evaluate your comfort level with risk, especially as you get closer to retirement.
- Beneficiary Designations: Ensure your beneficiaries are up-to-date, reflecting any life changes such as marriage, divorce, or new children.
- Overall Financial Goals: Confirm that your 401(k) strategy still aligns with your broader financial objectives, such as purchasing a home, funding education, or other significant life events.
Proactive management of your 401(k) is a hallmark of sound financial planning. By regularly reviewing and adjusting your contributions and investment strategy, you can adapt to changes and ensure your retirement savings continue to grow optimally, paving the way for a secure and comfortable future.
| Key Point | Brief Description |
|---|---|
| 2026 Limit | The standard employee contribution limit for 2026 is projected to be $23,000. |
| Catch-Up Contributions | Individuals aged 50 and over can contribute an additional $7,500, totaling $30,500. |
| Employer Match | Always contribute at least enough to receive the full employer matching contribution. |
| Roth 401(k) Option | Consider after-tax contributions for tax-free withdrawals in retirement, based on your tax outlook. |
Frequently Asked Questions About 2026 401(k) Contributions
The projected standard 401(k) contribution limit for employees in 2026 is $23,000. This amount does not include any matching contributions made by your employer, which are separate and additional to your personal limit.
Individuals who will be age 50 or older by December 31, 2026, are eligible to make catch-up contributions. The projected catch-up limit for 2026 is an additional $7,500, allowing eligible savers to contribute up to $30,500 in total.
To ensure you receive the full employer match, you must contribute at least the percentage of your salary that your employer specifies. Review your plan documents or consult your HR department to understand your company’s specific matching formula and contribute accordingly.
A Roth 401(k) allows for tax-free withdrawals in retirement, as contributions are made with after-tax dollars. A traditional 401(k) offers immediate tax deductions on contributions and tax-deferred growth. The best choice depends on whether you expect to be in a higher tax bracket now or in retirement.
Yes, the $23,000 limit (or $30,500 with catch-up) applies only to your personal contributions. Employer contributions are separate and do not count against your individual limit. The total contributions to your 401(k) from all sources can be much higher, up to an overall IRS limit (e.g., $69,000 in 2024).
Conclusion
Successfully maximizing your 2026 401(k) contributions: strategies for a $23,000 limit is a cornerstone of effective retirement planning. By understanding the standard contribution limits, leveraging catch-up provisions for older savers, and strategically optimizing employer matching programs, you can significantly enhance your financial security in retirement. Furthermore, considering the benefits of a Roth 401(k) and engaging in advanced strategies like the mega back-door Roth can provide additional tax advantages and growth opportunities. Regular review of your investment choices and overall financial plan ensures that your 401(k) remains aligned with your evolving goals. Proactive and informed decision-making today will pave the way for a more prosperous and worry-free future.
